

Dangote Q1 17 results – Strong results.
Dangote Cement published its Q1 17 numbers last Friday, posting EPS of NGN4.25, +36% yoy. Other highlights were: (1) revenue, +48% yoy and +20% qoq, to NGN208.1bn; (2) operating income, +48% yoy and 38% qoq, to NGN83.2bn; (3) pre-tax income, +42% yoy and 140% qoq, to NGN77.3bn; (4) net operating cash flow, +13% yoy to NGN99.0bn; and (5) gross debt down 11% ytd to NGN332.2bn.
Dangote Cement’s performance was commendable, in our view, driven by marked gains from selling price increases (+58% yoy) particularly those implemented in Nigeria. Earnings for the year are shaping up well, in line with management’s renewed commitment to improving the group’s profit margins even as the contribution from lower margin businesses increases. On a regional basis, the flagship Nigerian business drove group earnings, with operating profit up 62% yoy and an operating margin of 55%, up 7ppt yoy. The Pan African operations continue to record operating losses due to the high cost base in markets such as Tanzania and new operations such as Sierra Leone.
Key positives
§ Selling price increases – (+58% yoy and +4% qoq in Q1 17). Gains on selling price increases in Nigeria (+79% yoy and +10% qoq) really came through for the group during the period. Management intends to keep prices relatively stable to higher in order to maintain a robust level of EBITDA in dollar terms. In our view, there isn’t much room for further price increases until volumes react more drastically. That said, we note that Dangote Cement’s exports to neighbouring markets will continue to support volumes at current price levels.
§ Improvement in margins, sequentially – profit margins were mixed on a yoy basis with a slight improvement (+2ppt yoy) in our gross and EBITDA margins, while pre-tax margins declined 2% to 37%, which we believe was a result of higher contribution from the lower margin non-Nigerian businesses. Nonetheless, we find the sequential trend in key profit drivers encouraging, particularly pre-tax margins which were up 19ppt qoq to 37%. We expect a follow through in the next few quarters.
Key negatives
§ 6% yoy decline in volumes to 6.03mt, which includes the maiden contribution from Sierra Leone, that highlights the impact of: (1) sharp price adjustments on revenues; (2) a high base effect – volumes in Nigeria declined 16% yoy to 3.8mt (vs Q1 16 volumes of 4.5mt) but recovered by 17% qoq; and (3) moderating volumes in most non-Nigerian operations.
§ 51% yoy increase in group cost per tonne on account of new high-cost-base subsidiaries, the impact of devaluation on dollar-linked costs and translation of subsidiaries, albeit cost per tonne declined 18% qoq, reflecting strong cost management in Nigeria. This was a result of the use of its own coal to substitute LPFO; we note that local coal costs only 32% of LPFO and is not dollar-linked, unlike LPFO.
§ Higher net financing costs on account of shorter-term debts and the transfer to P&L of previously capitalised interest of new operations. In addition, interest rates were 3% higher and external debt rose due to the refinancing of Pan African funding.
§ Higher effective tax rate of 9% vs 3% in Q1 16 as a result of the expiration of some tax incentives related to Ibese.
Investment conclusion
§ The performance of the group supports our BUY recommendation and target price of NGN192. Our recommendation is based on: (1) the relatively strong earnings growth outlook; and (2) Dangote’s best-in-class operating model in Sub Saharan Africa – better profitability, regional footprint, its ability to consolidate market share in key markets, proactive cost management and FX risk mitigation in Nigeria.
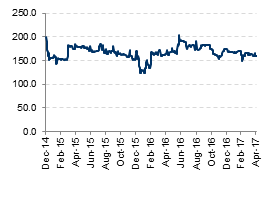
Stock price performance (DANGCEM NL)
Recommendations and opinions in this report, unless otherwise stated, are based on a combination of discounted cash flow analysis, ratio analysis, industry knowledge, logical extrapolations, peer group analysis and company specific and market technical elements (events affecting both the financial and operational profile of the company). Forecasting of company sales and earnings are based on segmented top-bottom models using subjective views of relevant future market developments. In addition, company guidance and financial guidance is taken into account where applicable. This report is on a stock under “active coverage”. All prices provided within this research report are taken from the close of business on the day prior to the issue date unless explicitly stated.
Exotic Partners LLP is authorised and regulated by the Financial Conduct Authority. Please see disclosures on the last page of this document.
Required Disclosures: http://www.exotix.co.uk/uploads/exotixpartnersllpresearchdisclosuresib.pdf.
DISCLOSURES
Analyst Certification
This document is independent investment research as contemplated by FCA Rule COBS 12.2 and is a research recommendation under FCA Rule COBS 12.4. Where it is not technically a research recommendation because the subject of the research is not listed on any European exchange, it has nevertheless been treated as a research recommendation to ensure consistent treatment of all Exotix’s research. This research has been produced by Moses Waireri Njuguna who is the Equity Analyst (the “Analyst”).
Exotix Research – Explanation of Research Recommendations
· Buy recommendation means – an upside of 15% or more within a trading range of 180 days.
· Sell recommendation means – a downside of 10% or more within a trading range of 180 days.
· Hold recommendation means – an upside or downside of less than the above within a trading range of 180 days.
The recommendations are based on data generally available in the market and reflect the prices, volatility, corporate information and general economic data available at the time of publication together with historical information in respect of the security(ies) or issuer(s). Further information in respect of the basis of any valuation is available from the analyst on request.
Conflicts of Interest
The analyst certifies that the views expressed in this research report accurately reflect his personal views about the subject securities or issuers. In addition, the analyst certifies that no part of his compensation was, is, or will be directly or indirectly related to the specific recommendations or views expressed in this research report.
Exotix Partners LLP, its subsidiaries and affiliated companies (“Exotix”) provide specialist investment banking to trading professionals in the wholesale markets. Exotix draws together liquidity and matches buyers and sellers so that deals can be executed by its customers. Exotix may at any time, hold a trading position in the securities and financial instruments discussed in this report. Exotix has procedures in place to identify and manage any potential conflicts of interests that arise in connection with its research. A copy of the Exotix Conflict of Interest policy is available at
www.exotix.com/regulatory-information.
Exotix Partners LLP does not generally produce maintenance research and as a result there is no planned frequency of research reports for securities under coverage, save that Exotix will aim to produce updates as appropriate and as soon as practicable. Other than this, research reports are produced on an ad hoc basis.
Comments
About Author